
- Agents face branded kiosk requirements and bans on co-locating other trades,
- principals must verify credit histories via bureaus, barring those with recent non-performing loans
- Super-agents need at least 50 active affiliates across Nigeria's six zones.
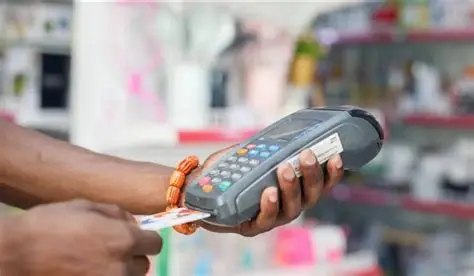
Point-of-Sale (PoS) operators across Nigeria warned on October 12, 2025, that the Central Bank of Nigeria’s (CBN) freshly issued agent banking guidelines could shutter small fintech firms and displace up to 40 percent of the sector’s 1.9 million workers, fostering monopolies among dominant players like OPay and Moniepoint. The Association of Mobile Money and Bank Agents in Nigeria (AMMBAN), representing these grassroots entrepreneurs, decried the policy’s mandate for agents to affiliate exclusively with one principal financial institution or super-agent starting April 1, 2026, as a threat to the multi-platform flexibility that sustains their livelihoods.
Issued via circular PSP/DIR/CON/CWO/001/049 on October 6, 2025, by Payments System Policy Director Musa I. Jimoh, the rules aim to curb fraud and enhance oversight in a market processing ₦10.51 trillion quarterly. For families relying on these informal hubs in bustling markets or remote villages, the shift evokes not just economic anxiety but a fear of eroded community lifelines, where a single downtime could once be bypassed by switching apps.
What the Policy Introduces: Key Provisions and Timeline
The CBN’s guidelines consolidate prior regulations while imposing new safeguards to professionalize agent banking, a channel born in 2013 that now boasts 8.36 million registered terminals, 5.9 million active, and 1,600 operators per square kilometer. Effective immediately except for exclusivity and location rules, they cap individual customer cash-outs at ₦100,000 daily and ₦500,000 weekly, with agents limited to ₦1.2 million cumulative daily across services. All transactions must route through dedicated principal-held accounts for traceability, and devices require geo-fencing to a 10-meter radius of registered spots, building on an August 2025 geo-tagging mandate extended to April 1, 2026.
Agents face branded kiosk requirements and bans on co-locating other trades, while principals must verify credit histories via bureaus, barring those with recent non-performing loans. Super-agents need at least 50 active affiliates across Nigeria’s six zones. Non-compliance invites blacklisting, ₦5 million fines minimum, or ₦20 million for unapproved ownership changes. The CBN frames this as advancing financial inclusion and curbing ₦4.45 trillion in illicit cash circulation as of August 2025, amid 20.12 percent inflation.
Why Operators Oppose It: Fears of Monopoly and Vulnerability
AMMBAN National President Fasasi Sharafadeen, speaking to Nairametrics, highlighted how exclusivity upends the shared model fueling competition among 200 providers, where five giants already hold 70 percent market share. “Agents thrive on redundancy; if OPay falters, PalmPay steps in,” he said, noting that forcing choices could strand users during outages and doom smaller fintechs reliant on pooled networks. Industry voice Chigozie Anayo echoed this, predicting divestments and exits that ripple to job losses for millions, many women and youth in informal setups blending PoS with petty trade for loan repayments.
Geo-tagging, meant to flag fraud via ISO 20022 messaging, draws fire for its 10-meter leash, impractical in fluid spots like motor parks where slight shifts halt service. Sharafadeen critiqued desk-bound policymaking: “Regulators overlook field grit; this ignores how agents multitask to eat.” With 80 percent of Nigerians bypassing banks for PoS convenience, these curbs risk reversing gains in a sector employing one per 80 citizens.
How the Rules Came About: CBN’s Rationale and Build-Up
The CBN, under Governor Olayemi Cardoso, seeks to mature a fragmented ecosystem plagued by arbitrage and laundering loopholes, where multi-homing blurred accountability. This follows August’s geo-tagging push for GPS-enabled devices, delaying validation to April amid upgrade hurdles for 4.2 million units. Earlier 2024 mandates routed transactions via aggregators like NIBSS and required CAC registration, formalizing what was once loosely structured. Aligned with global standards, the policy responds to POS’s explosive rise: ₦18.32 trillion in 2024 transactions, up 301 percent year-on-year, driven by fintechs in a $1.13 billion market eyeing $4.24 billion by 2033.
Yet, AMMBAN urges collaboration, as in past cash limit reversals, arguing enforcement without agent input repeats naira redesign woes.
Impacts on Nigerians: From Daily Hustle to Broader Economy
For PoS agents, often sole providers in underserved areas, exclusivity spells squeezed margins (0.3 percent commissions, ₦18-20 cap) and forced loyalty to unreliable principals, amplifying downtime risks in a nation where 89.76 percent of ₦5.01 trillion currency circulates outside banks. A Lagos trader juggling PoS and sales might abandon the venture, ceding ground to big fintechs and hiking fees for consumers already hit by 30-100 percent terminal price surges.
Nationally, it threatens financial inclusion for 40 million MSMEs, slowing rural cash access and stoking unrest in a youth-heavy economy with 42 percent unemployment. Positively, tighter controls could slash fraud, boosting trust and drawing $32.8 billion ICT growth by 2030. But without tweaks, experts like Akpan Ekpo warn of ATM neglect, urging focus on infrastructure over restrictions.
Analysis and Potential Outcomes: Balancing Regulation and Resilience
This policy fills oversight gaps but risks consolidation, mirroring Kenya’s 15 percent enrollment boost from flexible rules yet warning of Nigeria’s 20 percent Arts graduate parallel if rigidity prevails. Brookings-like analyses suggest exclusivity may professionalize via uniform KYC but erode competition, potentially halving small fintechs and widening urban-rural divides.
Optimistic paths include CBN revisions post-stakeholder input, extending timelines as with geo-tagging, fostering hybrid models. Pessimistically, mass deactivations by April 2026 could spike informal lending, fuel black markets, and dent GDP contributions from a sector adding N5 trillion via creatives by 2030. Success demands adaptive enforcement, perhaps pilot zones, to safeguard the human drive behind PoS’s quiet revolution.